Using Equity to Buy an Investment Property: How Usable Equity and Loan Splits Work
General Advice Warning: Tapping home equity increases your total outstanding liabilities and exposes your primary residence to financial risk. This explainer is educational in nature. Always consult an accredited credit licensee and a registered tax agent before refinancing home equity.
Quick Answer
Usable equity is the accessible wealth in your existing property calculated as 80% of its current bank valuation minus your outstanding mortgage balance. Rather than using cash savings, investors borrow against this usable equity as a separate loan split to fund the 20% deposit and stamp duty for a new investment dwelling, while securing the remaining 80% as a standalone mortgage against the new asset. Crucially, avoid cross-collateralisation by keeping both loans with independent securities.
For the vast majority of Australian property investors, purchasing a second or third dwelling does not require years of saving hundreds of thousands of dollars in cash. Instead, portfolio expansion is accelerated by releasing accumulated capital growth from an existing primary residence or prior investment asset.
However, tapping equity is not free money. It involves expanding your overall debt ledger and leveraging your home security. Structuring equity release incorrectly can contaminate tax deductions, expose your family home to forced foreclosure, and tie your assets into the dangerous trap of **cross-collateralisation** in your investment loan portfolio.
Total Equity vs Usable Equity: The 80% Rule
Homeowners often confuse their gross accounting equity with their accessible borrowing capacity:
- Total Equity: Current market value minus total mortgage balance. If your home is worth $1,200,000 and you owe $400,000, your total accounting equity is $800,000.
- Usable Equity: The portion a bank will permit you to borrow against without incurring Lenders Mortgage Insurance (LMI) or exceeding standard risk tolerances.
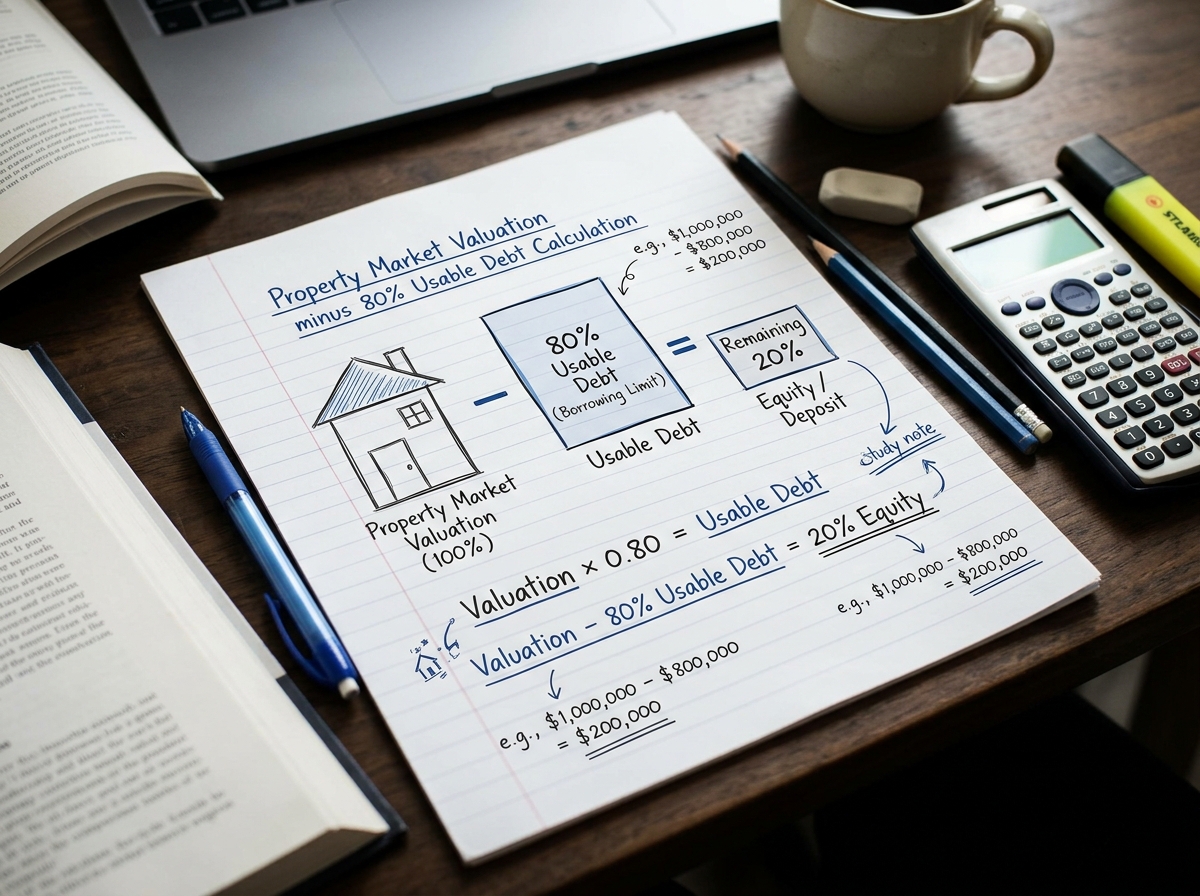
The mathematical formula for usable equity is:
Usable Equity = (Current Valuation × 0.80) − Existing Mortgage Debt
Using our $1,200,000 property example with a $400,000 debt:
- 80% of $1,200,000 = $960,000 (Maximum loan ceiling)
- $960,000 − $400,000 (Existing Debt) = $560,000 in Usable Equity.
Step-by-Step Mechanics: Funding a 100% Financed Purchase
By releasing usable equity, an investor can acquire a new property without committing a single dollar of cash savings, effectively achieving a 100% financed purchase through two distinct loans:
- Loan Split 1 (The Deposit Facility): Establish a new loan split of $160,000 (20% deposit) + $40,000 (stamp duty and costs) = $200,000, secured against your existing home’s usable equity.
- Loan Split 2 (The Main Investment Loan): Borrow $640,000 (80% of the new purchase price) secured exclusively against the newly acquired investment property.
Under this structure, both loans remain at or below 80% LVR, meaning **zero Lenders Mortgage Insurance** is payable on either security. To understand why bypassing LMI matters, review our explainer on LVR and LMI explained.
The Danger of Cross-Collateralisation: Why to Avoid It
When applying to tap equity, lazy mortgage brokers or direct bank branches frequently set up the lending using **cross-collateralisation** (also known as linking securities). Under cross-collateralisation, the bank links both properties under a single combined mortgage document.
This creates severe strategic disadvantages for investors:
| Dimension | Standalone Security Splits (Recommended) | Cross-Collateralised (Avoid) |
|---|---|---|
| Asset Protection | Properties are legally separate. Foreclosure on one does not automatically tie up the other. | Lender has a legal charge over all linked properties simultaneously. |
| Sale Proceeds Flexibility | If you sell the investment property, you keep all net capital profits after clearing its specific mortgage. | Bank can force you to use all sale proceeds to pay down your home loan before releasing funds. |
| Valuation Traps | A valuation drop on one asset does not impact borrowing against the other. | A price drop in one suburb drags down your overall portfolio equity assessment. |
ATO Tax Deductibility: The Purpose Test
A vital principle of Australian taxation law is the Purpose Test under Taxation Ruling TR 2000/2. The ATO dictates that tax deductibility of loan interest is governed entirely by the use of the borrowed funds, not by the asset used as mortgage security.
- Because the $200,000 equity split was borrowed for the explicit purpose of acquiring an income-producing rental asset, 100% of the interest on that equity loan split is tax-deductible, even though the loan is secured against your family home.
- Critical Warning: Never deposit equity funds into an everyday personal savings account or mix them with private funds before paying the deposit. Transfer funds directly from the newly created investment loan split to the conveyancer’s trust account to maintain an unbroken audit trail for the ATO.
Discover how deductible interest expenses contribute to net tax benefits in our comprehensive guide to negative gearing explained.
Frequently Asked Questions: Releasing Property Equity
Does releasing equity require refinancing my existing mortgage?
Not necessarily. If your current lender offers competitive interest rates and allows separate loan splits, you can simply request a top-up or secondary loan split against your existing property security. However, if your current lender has restrictive serviceability policies, refinancing both debts to a new institution may be required.
Can I tap equity if I am self-employed or have complex tax structures?
Yes. Self-employed borrowers can release home equity via traditional full-doc assessment (providing two years of lodged individual and company tax returns) or through specialized alternative-documentation (‘alt-doc’) loan products offered by non-bank lenders. Alt-doc products verify servicing using business bank transaction accounts or Business Activity Statements (BAS), albeit typically at slightly higher interest rate margins.
What happens to my equity loan if my home drops in value?
If residential property prices fall after you release equity, your overall LVR increases. However, Australian residential mortgages are standard ‘non-margin’ loans—as long as you continue meeting your monthly repayments on time, the bank will not issue a margin call or demand immediate cash injection to restore the 80% LVR ratio.
Serviceability Still Dictates What You Can Borrow
Holding $500,000 in usable equity does not guarantee a bank will lend it to you. A bank will only release equity if your household income can service the expanded debt repayments under current stress-testing rules. Review our underwriting guide on how serviceability is assessed to verify your net surplus cash flow before ordering property valuations.
Primary Sources & Authority References
- ATO – Taxation Ruling TR 2000/2: Deductibility of Interest on Borrowings.
- ASIC MoneySmart – Using Home Equity for Investment Property.
- MFAA – Mortgage & Finance Association of Australia Code of Practice.