How Serviceability is Assessed for Investment Property Loans in Australia
General Advice Warning: Credit assessment metrics described herein are general educational explanations of Australian banking underwriting policies. Lending limits, shading percentages, and expenditure benchmarks vary among Authorized Deposit-taking Institutions (ADIs). Consult an accredited mortgage broker or credit licensee for personalized calculations.
Quick Answer
Australian lenders assess investment loan serviceability by evaluating your Net Surplus Ratio (NSR) or Uncommitted Monthly Income (UMI). Rather than using your actual loan interest rate, banks stress-test all debt at a regulatory floor (typically contract rate + 3.00% APRA buffer). Furthermore, lenders haircut gross rental income by 20% to 30% (rental shading), benchmark living expenses against the Household Expenditure Measure (HEM), and assess credit card limits at 3.8% to 4.0% per month regardless of zero balances.
When property investors begin planning a residential acquisition, their focus is overwhelmingly drawn toward property searches, auction clearance rates, and suburb growth data. However, in the Australian regulatory environment, your portfolio acquisition trajectory is governed first and foremost by mortgage underwriting algorithms.
Under statutory responsible lending obligations enforced by the Australian Securities and Investments Commission (ASIC) and prudential standards set by the Australian Prudential Regulation Authority (APRA), banks do not evaluate what you believe you can afford. Instead, they apply standardized mathematical stress tests to determine your debt serviceability capacity across all existing and proposed commitments.
The Core Serviceability Equation: Net Surplus Ratio
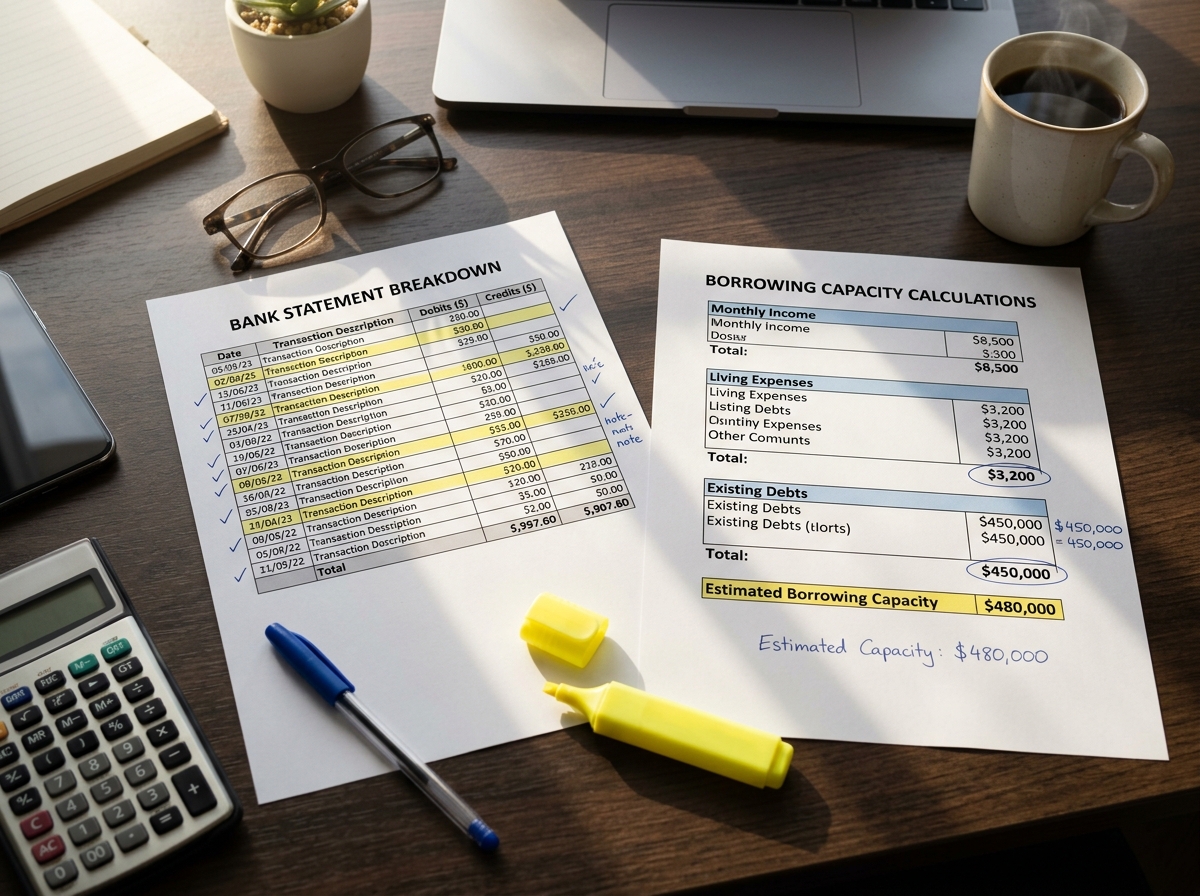
At its fundamental level, every bank borrowing calculator operates on the Net Surplus Ratio (NSR) or Uncommitted Monthly Income (UMI) calculation. The formula can be expressed as:
Net Surplus = (Verifiable Net Income + Shaded Rental Income) − (Living Expenses + Stressed Debt Commitments)
If the resulting figure is positive, serviceability is demonstrated. If the figure is even one dollar negative, the credit assessment automated scorecard will fail or require specialist credit exception approval.
How Lenders Treat Different Income Streams
Not all income is treated equally on an investment loan application. Banks categorize earnings by reliability and volatility:
| Income Type | Standard Lender Treatment | Underwriting Rationale |
|---|---|---|
| Base PAYG Salary | 100% of verifiable net earnings counted. | Stable, verifiable via payslips and ATO Notice of Assessment. |
| Overtime, Bonuses & Commissions | Discounted to 80%, or averaged over 2 years. | Discretionary and subject to economic cycles. |
| Proposed Rental Income | Shaded to 70% – 80% (20%–30% haircut applied). | Buffers against tenant vacancies, letting fees, rates, and repairs. |
| Self-Employed Profits | 2-year average of net taxable business profit. | Requires two consecutive years of lodged business tax returns. |
The Assessment Rate Buffer: Why Your Loan is Tested at 9%+
Perhaps the single largest impediment to investor borrowing capacity is the macroprudential stress buffer. Under APRA Prudential Practice Guide APG 223, Australian ADIs must evaluate new debt commitments at the higher of:
- The contract interest rate plus a minimum buffer of 3.00 percentage points.
- A minimum internal floor rate set by the lender (historically between 5.50% and 6.00%).
For example, if an investment loan is offered at a competitive variable rate of 6.25%, the bank’s credit system assesses the borrower’s monthly repayment as if the interest rate was 9.25% on a principal and interest amortization basis. This buffer alone strips hundreds of thousands of dollars in potential borrowing power from prospective buyers.
To examine the regulatory origins and mechanics of this requirement, read our comprehensive explainer on the APRA serviceability buffer explained.
Living Expenses: Stated Expenses vs The HEM Benchmark
Following regulatory enforcement by ASIC, lenders examine bank transaction statements using Open Banking data feeds to verify living expenses across multiple categories (groceries, insurance, utilities, private schooling, recreation). However, lenders apply a dual test:
- If your declared actual living expenses are higher than the Household Expenditure Measure (HEM) table (developed by the Melbourne Institute), the bank uses your higher declared figure.
- If your declared living expenses are lower than the statutory HEM benchmark for your family size and post-code demographic, the bank replaces your figure with the higher HEM figure.
Existing Liabilities: The Hidden Credit Card Multiplier
Existing debts can drastically erode serviceability capacity. Credit cards are evaluated based on their total credit limit, regardless of whether you pay the balance in full every month:
Most Australian lenders assess an existing credit card limit at 3.8% to 4.0% per month as a continuous debt commitment. For example, a $20,000 credit card limit—even with a $0 balance—is treated as an ongoing liability of $760 to $800 per month ($9,120 to $9,600 per year in debt repayments). Under standard debt-service ratios, this $20,000 credit limit reduces your borrowing capacity by roughly $80,000 to $100,000.
When structuring your loan facilities, also pay close attention to your loan-to-value gearing ratios. Review our guide on LVR and LMI explained to balance borrowing power against mortgage insurance expenses.
Worked Numerical Example: Calculating Investor Capacity
Consider an investor couple earning $180,000 combined gross PAYG salary, seeking to purchase an investment dwelling generating $650 per week in rental income:
- Net Household Income: Approximately $11,200 per month after tax.
- Gross Anticipated Rental Income: $650/week = $2,816/month. Shaded at 80% = $2,253/month.
- Total Monthly Income Credited: $11,200 + $2,253 = $13,453/month.
- Declared Living Expenses (HEM benchmark): $4,800/month.
- Existing Owner-Occupied Home Loan ($500,000 balance @ 6.0%): Assessed at 9.0% over remaining 25-year term = $4,196/month.
- Net Monthly Surplus for New Debt: $13,453 − ($4,800 + $4,196) = $4,457/month.
At a stressed test rate of 9.25% on a 30-year term, that $4,457 surplus permits a maximum new investment borrowing capacity of approximately $540,000.
If you already own an established home with built-up wealth, you can tap into this equity to fund your deposit. Learn how this interacts with serviceability in our guide on using equity to buy an investment property.
Practical Strategies to Maximize Serviceability
To optimize borrowing power before lodging a formal credit application:
- Cancel Unnecessary Credit Cards: Close or reduce card limits to the bare minimum 30 days prior to applying.
- Audit Discretionary Expenses: Review gym subscriptions, delivery apps, and streaming memberships to ensure bank feeds show clean expense patterns.
- Consolidate Personal Debt: Eliminate personal loans, car finance, and Buy-Now-Pay-Later (BNPL) accounts that carry high monthly repayment burdens.
- Compare Tier-2 Lenders: Non-major banks and regional building societies often utilize different assessment floors and more generous rental shading policies.
Primary Sources & Authority References
- Australian Prudential Regulation Authority (APRA) – Prudential Practice Guide APG 223: Residential Mortgage Lending.
- Reserve Bank of Australia (RBA) – Financial Stability Review: Household Sector Resilience.
- Melbourne Institute – Household Expenditure Measure (HEM) Methodology.